The KYC Handoff Problem: Who Owns Compliance When You're Using Embedded Finance?

Wednesday, 10 June 2026|3 mins. read
The KYC Handoff Problem: Who Owns Compliance When You're Using Embedded Finance?
Where Ownership Becomes Blurred

In a typical embedded finance setup, KYC is performed by a third-party provider.

From a product perspective, this feels efficient. Verification is outsourced. Integration is quick. The platform moves faster.

But compliance does not disappear. It shifts.

If a transaction is flagged, who is responsible for the investigation? If user data is incomplete, who is accountable? If regulators request audit records, who provides them?

The platform still owns the user relationship.

Which means it often inherits the consequences of compliance gaps, even when it does not control the full process.

The Illusion of Delegated Compliance

Many platforms assume that using a KYC provider transfers compliance responsibility.

It does not.

It transfers execution, not ownership.

Regulators evaluate the full system, not just the component that performed identity verification. They look at how data flows, how decisions are made, and how transactions are monitored over time.

If KYC is disconnected from transaction monitoring or payment flows, risk increases.

A verified user at onboarding can still become a compliance risk during activity.

Without coordination across systems, those signals are missed.

Data Ownership and Fragmentation

KYC introduces another layer of complexity: data ownership.

User identity data may sit with a verification provider. Transaction data may sit with a payment processor. Account data may sit with a banking partner.

When these systems are not aligned, visibility breaks down.

This creates challenges in three areas:

Audit readiness. Reconstructing user activity across systems becomes time consuming.

Risk management. Incomplete data leads to delayed or inaccurate decisions.

User experience. Re-verification requests appear inconsistent and repetitive.

What should be a single compliance flow becomes fragmented across multiple providers.

Why This Becomes a Product Problem

From the user's perspective, none of this complexity matters.

They expect onboarding to be smooth. They expect transactions to be predictable. They expect their account to function without interruption.

When KYC systems are not coordinated, friction appears.

Users are asked for the same information multiple times. Transactions are paused without clear explanation. Accounts are restricted unexpectedly.

These are not compliance failures in isolation. They are product failures.

Designing for Clear Ownership

The solution is not to eliminate third-party providers. It is to design for clarity.

Platforms need to define ownership at the system level.

Who controls user identity data? How KYC signals feed into transaction monitoring. How compliance decisions are logged and explained. How audit trails are maintained across the lifecycle of a user.

At PCXPay, compliance infrastructure is designed to unify these layers.

KYC, transaction monitoring, and payment execution operate within a coordinated system. Data flows are structured so that identity, activity, and risk signals remain connected.

This ensures that compliance is not lost between providers.

It remains visible, traceable, and enforceable.

A Better Way to Think About KYC

KYC is not a step in onboarding.

It is a continuous process that extends across the entire lifecycle of a user.

Treating it as a one-time event creates blind spots.

Designing it as part of your infrastructure creates control.

If your current setup makes it difficult to answer a simple question like who owns compliance at each stage of a transaction, the system may need to be rethought.

Learn how PCXPay helps platforms unify KYC, transaction monitoring, and payment infrastructure into a single, coordinated system built for scale and regulatory clarity.
#embeddedfinance#kyc#compliance#systemdesign#regtech#fintechinfrastructure

Other Stories

US to Kenya: M-Pesa Dominance and Platform Strategy

US to Kenya: M-Pesa Dominance and Platform Strategy

Many global payment teams make the same mistake when entering African markets. They assume payments behave the same way everywhere. A product succeeds in the US using cards and bank transfers, so the expectation is simple: connect a few payment APIs, enable local currency support, and expansion should work. Then Kenya happens. Because in Kenya, payments are not built around cards. They are built around mobile money and more specifically, around M Pesa. For platforms entering the region, this changes everything from onboarding flows to settlement logic, transaction design, customer behavior, and infrastructure strategy itself.

Wednesday, 9 September 2026

Read More
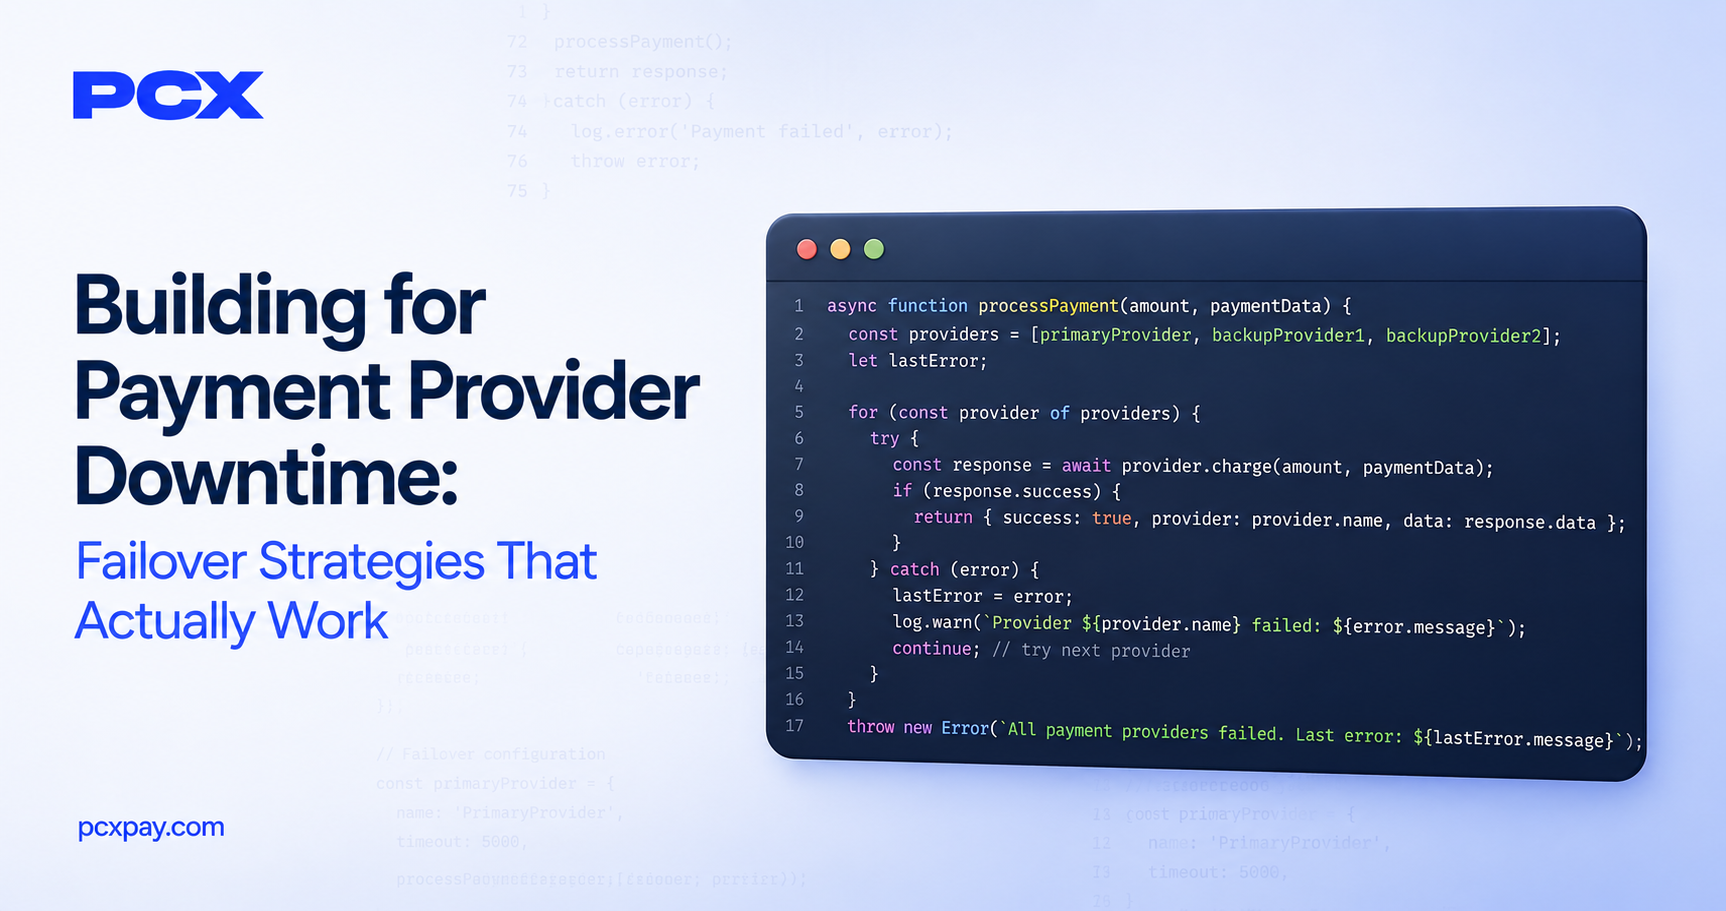
Building for Payment Provider Downtime: Failover Strategies That Actually Work

Building for Payment Provider Downtime: Failover Strategies That Actually Work

Payment infrastructure rarely fails all at once. What usually happens is far more dangerous. A provider remains technically "online", but transaction approvals begin slowing down. Settlement confirmations arrive inconsistently. Certain corridors quietly fail while dashboards continue showing green uptime indicators. Support tickets increase before monitoring systems even detect a problem. At a small scale, these disruptions feel temporary. Teams wait for providers to recover and manually resolve exceptions later. At platform scale, that approach breaks quickly. Because downtime in modern payments is rarely binary. It is partial, fragmented, and unpredictable. And the systems that survive these moments are not necessarily the systems with the best providers. They are the systems designed to continue operating when providers become unreliable.

Thursday, 27 August 2026

Read More
Why Your Retry Logic is Probably Costing You Money

Why Your Retry Logic is Probably Costing You Money

Most payment systems treat retries as a safety mechanism. A transaction fails, the system tries again, and success rates improve. At least in theory. In practice, poorly designed retry logic often creates hidden operational costs that become more expensive as transaction volume grows. Duplicate processing, unnecessary routing fees, delayed settlements, partner strain, and inflated infrastructure usage are all common side effects of retry systems designed around brute force repetition rather than intelligent orchestration. Retries solve failure. But unmanaged retries can also amplify it.

Friday, 21 August 2026

Read More
Multi-Currency Wallets: Simple Concept, Complex Execution

Multi-Currency Wallets: Simple Concept, Complex Execution

Multi-currency wallets appear deceptively simple from the outside. Hold multiple balances. Convert between currencies. Send and receive funds across regions. For users, the experience feels straightforward. Behind the infrastructure layer, however, multi-currency systems are one of the most operationally complex products payment platforms can build. Because supporting multiple currencies is not simply about displaying different balances. It requires coordinating settlement behaviour, liquidity management, FX exposure, compliance obligations, and transaction visibility across entirely different financial systems simultaneously. The complexity begins long before the first currency conversion occurs.

Friday, 14 August 2026

Read More
The "1,000 Transactions" Trap: Why Early Payment Success Doesn't Scale

The "1,000 Transactions" Trap: Why Early Payment Success Doesn't Scale

The first thousand transactions usually create a dangerous kind of confidence. Payments appear stable. Reconciliation feels manageable. Support tickets stay low. Dashboards look healthy. From the surface, the infrastructure seems ready for growth. Then volume increases. Suddenly, retries begin stacking. Settlement mismatches become harder to trace. Transaction delays appear across specific corridors. Finance teams start escalating inconsistencies engineering teams cannot immediately reproduce. What worked perfectly at low volume begins failing under operational pressure. This is one of the most common traps in payment infrastructure. Early payment success is not proof of scalability. It is often proof that the system has not yet been stressed.

Wednesday, 5 August 2026

Read More
Why "Free" Payment APIs Cost More Than You Think

Why "Free" Payment APIs Cost More Than You Think

"Free" is one of the most effective words in fintech marketing. Free API access. Free integrations. Zero setup costs. For early-stage companies moving quickly, these offers feel compelling. A few lines of code, a sandbox environment, and payments appear operational within days. From the outside, it looks like infrastructure has become commoditised. But payment infrastructure is rarely free. The cost simply moves somewhere less visible.

Wednesday, 29 July 2026

Read More

Make Money Borderless

Stop building payment infrastructure. Start shipping features that matter. Join the platforms already moving money globally with PCX.